When people talk about what they hope to leave their children, they usually talk about money.
A house.
A savings account.
Investments.
Jewelry.
Maybe a collection of something nobody in the family actually wants but everyone is afraid to throw away.
But there is another inheritance that may matter even more.
A plan.
Because someday, your children may have to step into your life when you can no longer manage everything yourself.
And when that day comes, the greatest gift you can give them is not a bigger bank account.
It is clarity.
They should know what you want.
They should know where things are.
They should know who has authority to act.
They should know which accounts exist.
They should know what bills need to be paid.
They should know what your medical wishes are.
They should know where your important documents are kept.
In other words, they should not have to become detectives while they are grieving.
At Elderhood.info, we talk a lot about aging smarter, not harder. One of the six ideas behind that philosophy is simple: prepare smarter.
Preparation is not prediction.
It is protection.
Your Family Should Not Have to Guess
Imagine this situation.
A parent suddenly becomes seriously ill.
One child is trying to find the will.
Another is searching through drawers for insurance policies.
Someone else is trying to figure out which bank holds the checking account.
Nobody knows the computer passwords.
Nobody knows whether there is a healthcare proxy.
Nobody knows whether there is a power of attorney.
And everybody keeps saying the same thing:
“I thought somebody else knew.”
That is how family chaos begins.
Not because people do not care.
Because nobody prepared.
The National Institute on Aging recommends advance care planning precisely because medical decisions may eventually need to be made when someone can no longer speak for themselves. Advance directives can include instructions about care and can identify someone to make healthcare decisions on your behalf.
That is not morbid.
That is practical.
Start With the Documents That Matter Most
The first step is knowing which documents may become important.
Depending on your situation and state law, those may include:
- A will
- A durable financial power of attorney
- A healthcare proxy or healthcare power of attorney
- A living will or advance directive
- Trust documents, if applicable
- Beneficiary designations
- Life insurance information
- Property deeds
- Vehicle titles
- Funeral or burial instructions
You do not need to become your own lawyer.
In fact, legal documents should be prepared properly, and state requirements vary.
But you should know what you have, what you need, and where the documents are located.
A financial power of attorney, for example, allows another person to act on your behalf under the authority granted in the document. The Consumer Financial Protection Bureau notes that without advance planning, families may sometimes need to pursue a court-appointed guardian if someone becomes unable to manage their own affairs.
That is a lot more complicated than signing the right documents while you are still fully capable of making your own decisions.
A Will Is Important — But It Is Not the Whole Plan
Many people think:
“I have a will. I am all set.”
Not quite.
A will primarily addresses what happens after death.
But what happens if you are alive and cannot manage your finances?
Who pays your mortgage?
Who pays the utility bill?
Who handles your insurance?
Who deals with the bank?
Who speaks with financial institutions?
That is why a power of attorney can be just as important as a will.
Likewise, a will does not automatically tell doctors what medical treatment you would want if you cannot communicate.
That is where healthcare directives and proxies become important.
The real goal is not one document.
It is a complete system.
Tell Someone Where Everything Is
This sounds almost embarrassingly simple.
But it may be one of the most important steps of all.
You can have the finest estate plan in America, but if nobody knows where it is, it is not very useful in an emergency.
Create one known location for your important information.
It could be:
A fireproof file box.
A locked filing cabinet.
A home safe.
A secure digital vault.
Or a combination.
Then tell the appropriate person where it is.
You do not necessarily have to hand over every document today.
But someone should know how to find them.
That basic idea fits closely with Elderhood’s broader approach to creating smarter systems for later life: make the right thing easier before you urgently need it.
Create a Financial Map
Your children may not need access to your money today.
But they may eventually need to know where it is.
Create a simple list of your financial world.
You can include:
- Bank accounts
- Brokerage accounts
- Retirement accounts
- Pensions
- Social Security information
- Credit cards
- Mortgages
- Loans
- Insurance policies
- Safe-deposit boxes
- Property
- Vehicles
- Regular monthly bills
You do not need to put every account number in an unsecured notebook lying on the kitchen counter.
Security still matters.
But someone should be able to identify what exists.
The CFPB specifically recommends planning ahead for who might help manage money and property if needed. It also provides guidance for people acting under powers of attorney, trusts and other fiduciary arrangements.
A good financial map saves time.
More importantly, it reduces mistakes.
Review Your Beneficiaries
This is one of the easiest things to neglect.
You may have named a beneficiary on a retirement account 20 years ago.
Has your family situation changed since then?
Has there been a divorce?
A death?
A remarriage?
A new child or grandchild?
Beneficiary designations can be extremely important because certain accounts pass according to the beneficiary designation rather than the instructions in a will.
That is why these designations should be reviewed periodically.
Do not assume they are still correct.
Check.
Passwords Are Now Part of Estate Planning
This is a modern problem our parents did not have.
Your life is increasingly digital.
Email.
Online banking.
Investment accounts.
Insurance portals.
Social media.
Cloud storage.
Subscriptions.
Cell phone access.
Utility accounts.
Streaming services.
Healthcare portals.
If nobody can access any of it, settling your affairs may become much harder.
That does not mean handing your passwords to half the family.
It means creating a secure system.
You may use a reputable password manager, secure written record, or other method that allows a trusted person to gain access when appropriate.
The key question is simple:
If I were unable to log in tomorrow, could the right person figure out what to do?
If the answer is no, you have found a hole in your plan.
Your Healthcare Wishes Matter Too
This is not just about money.
It is also about dignity.
Suppose you are seriously ill and unable to communicate.
Would your family know what kind of care you would want?
Would they know your wishes regarding life-sustaining treatment?
Would they know who you trust to make decisions?
Or would they be forced to guess?
Advance care planning can reduce that uncertainty.
The National Institute on Aging explains that advance directives can help people document future healthcare preferences and designate a healthcare proxy to act when the patient cannot communicate.
This can also reduce conflict among family members.
When your wishes are clear, your children do not have to argue about what they think you would have wanted.
You have already told them.
Choose the Right Person, Not Just the Closest Person
This is important.
The person you choose to handle your finances or healthcare decisions does not automatically have to be your oldest child.
Choose the person who is best suited for the role.
One child may be excellent with finances.
Another may be emotionally stronger in medical situations.
Another may live across the country and be difficult to reach quickly.
Another may simply not want the responsibility.
That matters too.
A fiduciary has legal responsibilities when managing another person’s property. The CFPB emphasizes duties such as acting in the person’s best interest, managing money carefully, keeping funds separate, and maintaining good records.
So choose carefully.
And ask the person before putting their name on important documents.
Surprise birthday parties are fine.
Surprise fiduciary responsibilities are not.
Talk to Your Family While You Can
One of the biggest mistakes people make is avoiding these conversations because they are uncomfortable.
“I do not want to upset the kids.”
“I do not want to talk about dying.”
“I will get around to it.”
Then something happens.
And suddenly nobody has time for the conversation that should have happened five years earlier.
You do not have to make it dramatic.
You can simply say:
“I have organized my important papers. Here is where they are. Here is who I want making decisions if I cannot. Here is what I want you to know.”
That is enough to begin.
In many ways, that conversation may be more important than the documents themselves.
Preparation Can Help Protect Against Financial Exploitation
There is another benefit to planning ahead.
Older adults can become vulnerable to financial fraud, scams and exploitation.
The CFPB and FDIC have developed resources specifically to help older adults and caregivers recognize and prevent financial exploitation.
Having trusted people involved, establishing powers of attorney appropriately, monitoring accounts and keeping clear records may help reduce some of that risk.
Again, this is not about giving away control.
It is about creating a backup system.
As long as you are capable, you remain in charge of your own affairs.
The goal is to make sure the right person can step in if necessary.
Do Not Wait for a Diagnosis
There is a dangerous tendency to delay this kind of planning until something goes wrong.
A dementia diagnosis.
A stroke.
A fall.
A hospitalization.
A cancer diagnosis.
But that is often the worst time to start.
The better time is when nothing is wrong.
When you are thinking clearly.
When you can ask questions.
When you can make deliberate choices.
When you can change your mind if necessary.
This is part of the larger Elderhood philosophy we discuss in articles such as Elderhood Is Not Decline: It Is the Art of Staying Fully Alive and The Science of Elderhood.
Aging well is not only about exercise, nutrition and medical care.
It is also about maintaining control.
Preparation is one way to do that.
Make a Simple “If Something Happens to Me” File
If the whole process feels overwhelming, start with one folder.
Write on the front:
If Something Happens to Me
Inside, place or reference:
Your will.
Power of attorney.
Healthcare proxy.
Advance directive.
Insurance information.
Account list.
Important contacts.
Medication list.
Doctors.
Funeral wishes.
Passwords or instructions for accessing them securely.
Property information.
Beneficiary information.
You can expand it later.
Perfection is not required.
Organization is.
Review It Once a Year
Life changes.
Accounts close.
Banks merge.
Passwords change.
People die.
Relationships change.
Doctors change.
Insurance changes.
That means your plan should be reviewed regularly.
Pick one date each year.
Your birthday.
New Year’s Day.
The first day of spring.
Any date you will remember.
Take 30 minutes and ask:
Is everything still accurate?
Are the right people still named?
Do they still know where everything is?
Has anything important changed?
Thirty minutes once a year can prevent days or weeks of confusion later.
This Is Not About Death
That may be the most important point.
Planning your affairs is not about obsessing over death.
It is about protecting life.
Your independence.
Your wishes.
Your family.
Your dignity.
It is about making sure that if something happens, the people who love you can act instead of panic.
There is a line at Elderhood that captures this perfectly:
Preparation is not prediction. It is protection.
And maybe we should add another:
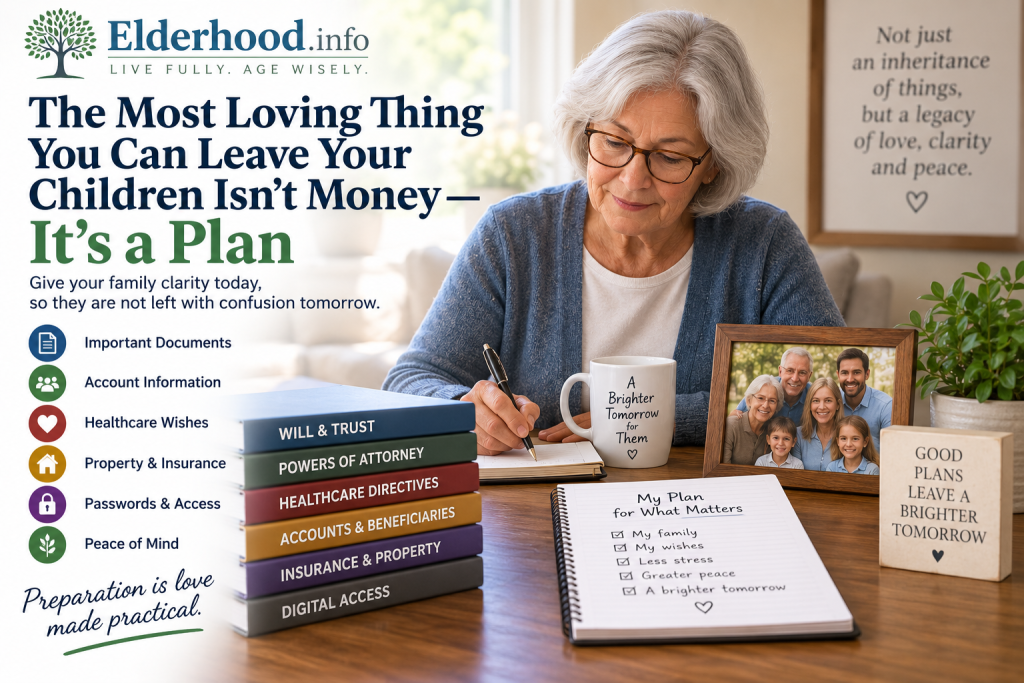
Preparation is love made practical.
You may leave your children money.
You may leave them property.
You may leave them photographs, stories and memories.
But one of the most loving things you can leave them is something much simpler.
A clear plan.
Because someday, during one of the hardest weeks of their lives, they may open that folder and realize something.
You thought about them before they ever needed you to.
And that may be one of the greatest gifts you ever gave them.