Nobody enjoys talking about death.
We would rather discuss almost anything else.
The weather.
The grandchildren.
The price of groceries.
Why the television remote now requires a degree in electrical engineering.
But there is one conversation many older adults continue to avoid, and avoiding it can leave the people we love with an enormous mess at exactly the moment they are least equipped to handle one.
That conversation is this:
What happens when I die?
Not philosophically.
Practically.
Where is my will?
Who is supposed to make medical decisions if I cannot?
Who has power of attorney?
Where are my financial accounts?
Who are the beneficiaries?
Where are the insurance policies?
What happens to the house?
Where are my passwords?
What do I want done with my belongings?
And perhaps most importantly:
Does anyone in my family actually know where any of this information is?
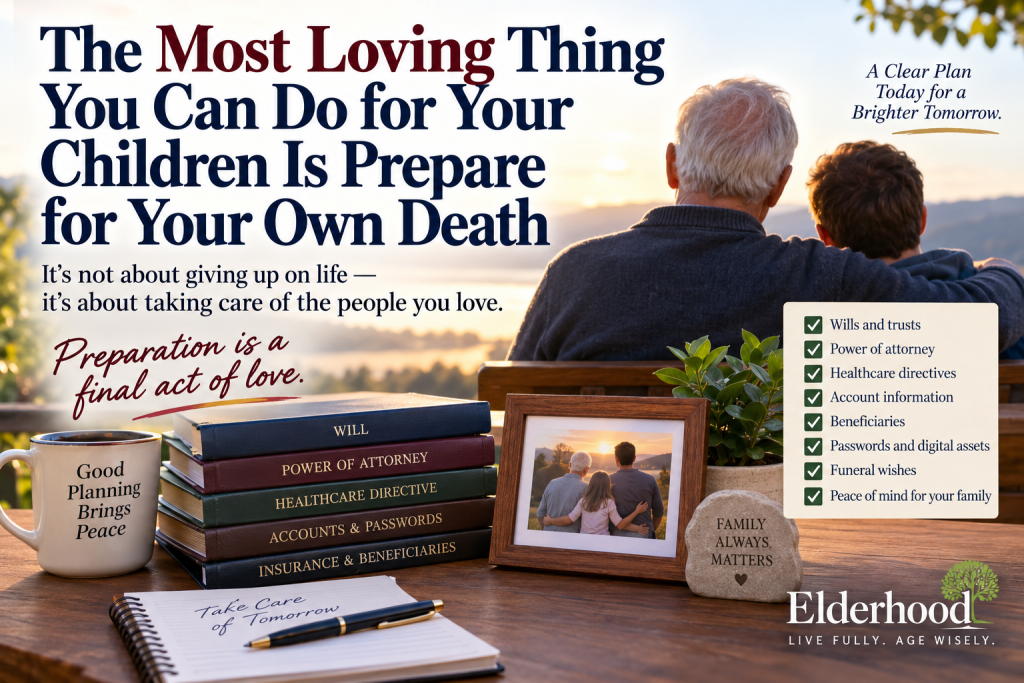
Preparing for your death is not giving up on life.
It is one of the most loving things you can do for the people who may someday have to carry on without you.
We Prepare for Everything Except the One Thing We Know Will Happen
Think about how much preparation we do throughout life.
We prepare for retirement.
We insure our homes.
We insure our cars.
We save for emergencies.
We buy smoke detectors.
We keep spare tires.
Some of us even buy extended warranties for refrigerators that will probably outlive us.
But when it comes to death—the one event with a 100-percent historical success rate—we suddenly become optimistic.
“I’ll take care of that someday.”
Someday has a terrible habit of arriving before the paperwork does.
This is why Elderhood includes what we call Prepare Smarter.
Preparation is not prediction.
It is protection.
And it is protection not only for you, but for the family members who may someday have to make difficult decisions on your behalf.
You can explore more of the Elderhood philosophy of preparing while still living fully at Elderhood.info.
Don’t Make Your Children Become Detectives
Imagine someone you love has just died.
You are grieving.
You are exhausted.
Maybe you have traveled across the country.
And now someone hands you an invisible detective badge.
Find the will.
Find the bank accounts.
Find the life insurance.
Find the passwords.
Find the title to the car.
Find out who owns what.
Figure out which bills are automatically being paid.
Figure out whether there is a safe-deposit box.
Find the lawyer.
Find the accountant.
Find the funeral instructions.
Find the healthcare paperwork.
That is a tremendous burden to place on someone.
And it is largely preventable.
You do not have to eliminate every problem.
You simply have to leave a map.
Start With a Will
A will is one of the basic building blocks of estate planning.
It tells others how you want certain property distributed and identifies who should handle your estate.
But simply creating a will is not enough.
Someone needs to know that it exists.
And someone needs to know where the original is located.
Putting the world’s most beautifully prepared estate plan in a locked drawer nobody knows about is only slightly better than not having one.
Laws governing wills, witnesses, notarization, probate and estates vary by state, so this is one area where professional legal advice can be valuable.
Do not assume something you downloaded from the internet automatically satisfies the requirements where you live.
The goal is not just to have paperwork.
The goal is to have paperwork that works when somebody needs it.
Power of Attorney Matters Before Death
A will generally addresses what happens after death.
But another question may become important before that:
What happens if you are alive but unable to manage your own affairs?
A serious accident, stroke, cognitive decline or hospitalization can make it temporarily or permanently impossible to handle banking, bills, contracts or other financial matters.
That is where an appropriate power of attorney can become important.
A properly prepared power of attorney can authorize a person you trust to handle certain financial or legal matters if circumstances require it.
The details vary by state, and the authority you grant can be broad or limited.
This is not a document to sign casually.
Choose the person carefully.
Trust matters enormously when you are giving someone access to your financial life.
Who Speaks for You When You Cannot Speak?
Money is only part of the picture.
What about healthcare?
The National Institute on Aging recommends advance care planning so that your wishes can be known if you become unable to make or communicate medical decisions yourself. A healthcare proxy—sometimes called a healthcare agent or surrogate—can make medical decisions for you under the appropriate advance-directive documents.
This is one of those subjects people tend to postpone because they imagine it applies only to somebody lying in a hospital at age 98.
It does not.
A serious accident or stroke can happen unexpectedly.
The question is not:
“Do I expect something terrible to happen?”
The question is:
“If something happens, do the people around me know what I want?”
Your healthcare proxy should not simply have a name on a form.
That person should understand your values.
Talk to them.
Tell them what matters to you.
Tell them what kind of care you would want.
Tell them what quality of life means to you.
The National Institute on Aging also recommends sharing copies of advance directives with the people who may need them, including your healthcare proxy and medical providers.
A document nobody can find during an emergency is not especially helpful.
Check Your Beneficiaries
Another overlooked area is beneficiary designations.
Retirement accounts, insurance policies and certain financial accounts may allow you to name beneficiaries directly.
Those designations deserve periodic review.
Life changes.
People divorce.
People remarry.
Children grow up.
Beneficiaries die.
Relationships change.
Accounts get transferred from one company to another.
Yet the beneficiary designation may still reflect a decision made decades earlier.
Do not assume your will automatically overrides every beneficiary designation.
Estate law and account rules can be complicated.
Review them periodically and ask your financial or legal professional when you are unsure.
Make a Master List of Your Accounts
Your family does not necessarily need immediate access to all your money.
But somebody should eventually be able to determine where everything is.
Create a list of your major financial relationships.
Bank accounts.
Investment accounts.
Retirement accounts.
Pensions.
Life insurance.
Annuities.
Mortgages.
Credit cards.
Loans.
Property.
Vehicles.
Business interests.
Safe-deposit boxes.
You do not necessarily need to put every account number on a sheet taped to the refrigerator.
Security still matters.
But your executor or trusted family member needs enough information to locate what exists.
Think of it as leaving breadcrumbs.
Preferably better breadcrumbs than Hansel and Gretel had.
And Then There Are the Passwords
Previous generations did not have this problem.
Grandpa might have left behind a checking account, a house key and an old Buick.
Today we leave behind a digital civilization.
Email accounts.
Banking websites.
Phones.
Computers.
Cloud storage.
Social media.
Photo libraries.
Subscription services.
Streaming accounts.
Online businesses.
Domain names.
Cryptocurrency in some cases.
And 47 passwords containing combinations of capital letters, punctuation marks and the name of somebody’s first dog.
Digital access has become part of estate preparation.
You need a secure system for storing passwords and instructions and a trusted person who knows how to locate that system when necessary.
Do not simply send all your passwords around by email.
Use an appropriate secure method, and consider professional advice for valuable digital assets.
The important thing is that your digital life should not become permanently inaccessible because nobody knew where you kept the keys.
Tell Them What You Want Done
Families frequently end up fighting about things the deceased person could have settled with a five-minute conversation.
Who gets Mom’s jewelry?
What happens to Dad’s tools?
Who gets the photographs?
Should the house be sold?
What happens to the dog?
Burial or cremation?
Religious service or no service?
Large funeral or small gathering?
Sometimes the fights are not really about the object.
They are about grief, memory and old family tensions that suddenly get attached to a dining-room table.
Writing down your preferences can help.
Not every personal wish necessarily belongs in a legal will. Your attorney can advise you on what should be legally documented and what can simply be communicated separately.
But communication matters.
Silence leaves room for arguments.
Social Security Does Not Simply Continue
Families should also understand that Social Security benefits change when a beneficiary dies.
Social Security says retirement benefits end with the beneficiary’s death; a payment is not due for the month of death. Certain surviving spouses, former spouses, children and dependent parents may qualify for survivor benefits instead.
Funeral homes usually report deaths to Social Security, although families should verify that the notification occurs.
This is another reason spouses should understand household finances before a crisis occurs.
One partner should never be completely in the dark simply because the other partner “always handled the money.”
That arrangement may work wonderfully for 50 years.
Then one morning it doesn’t.
Create One Place Where Everything Can Be Found
One of the simplest things you can do is establish one clearly identified place containing—or pointing to—your important information.
It might be a fire-resistant home safe.
A secure filing cabinet.
A document organizer.
A secure digital vault combined with physical instructions.
Whatever system you choose, the key is that somebody you trust knows where it is.
Your file might contain or identify:
Your will.
Trust documents, if applicable.
Power-of-attorney documents.
Healthcare proxy and advance directives.
Insurance information.
Financial account list.
Beneficiary information.
Property documents.
Key professional contacts.
Funeral preferences.
Digital-account instructions.
Important identification documents.
Information about recurring bills and subscriptions.
You do not necessarily need to hand your entire financial life to your children today.
You just need to make sure they are not searching through 25 years of desk drawers while grieving.
Have the Conversation While You Can
There is something else paperwork cannot do.
Paper cannot explain you.
Your children may know your signature.
They may not know your wishes.
Sit down and talk.
Not during Thanksgiving dinner between the turkey and pumpkin pie.
Pick a quiet time.
Tell them what you have prepared.
Tell them where the documents are.
Explain who you appointed and why.
Tell them whether there are any surprises they should know about.
And give them permission to ask uncomfortable questions.
The conversation may feel awkward for the first five minutes.
Then something interesting often happens.
Everyone feels better.
Because uncertainty is frightening.
Clarity is comforting.
Preparation Gives You More Freedom to Live
Here is the irony.
Getting your affairs in order does not make you think about death more.
Often, it allows you to think about it less.
Once you know the important pieces are handled, you can get back to living.
Travel.
Dance.
Learn something new.
Spend time with people you love.
Work on your health.
Start another chapter.
As we discuss in The Next Chapter May Still Be Waiting, elderhood does not mean the story is finished.
Preparation and optimism are not opposites.
They belong together.
You wear a seatbelt because accidents happen.
That does not mean you expect to crash every time you drive to the supermarket.
Estate preparation works the same way.
Don’t Leave Love in the Form of a Mess
Most parents would do almost anything for their children.
They help with tuition.
Weddings.
Grandchildren.
Emergency loans.
Moves.
Divorces.
Career disappointments.
Broken hearts.
And sometimes at 80 years old they are still worrying about whether their 55-year-old child remembered to bring a sweater.
That instinct never really disappears.
So here is one final way to take care of them.
Leave your affairs organized.
Leave clear instructions.
Leave the right documents.
Leave names and phone numbers.
Leave your wishes.
Leave a map.
Because someday, your family may be dealing with the sadness of losing you.
They should not also have to deal with the chaos of trying to reconstruct your life from unopened envelopes and forgotten passwords.
Preparing for your death is not surrender.
It is responsibility.
It is wisdom.
And perhaps most of all, it is love.
At Elderhood, we believe aging well means more than staying alive.
It means taking care of yourself, preparing intelligently for tomorrow and making life a little easier for the people who come after you.
Preparation is not prediction. It is protection.
And one day, the people you love may be very grateful that you took the time to do it.